All Categories
Featured
Evaluating PPO vs HMO Medical Coverage
Table of Contents
Knowing the distinctions in between specific health plans, like an HMO and a PPO plan, is required to protect the ideal health protection for you, your family, or your workers. In this post, we'll stroll you through the essential distinctions in between HMO and PPO plans, examine their pros and cons, and show you how each plan deals with a health reimbursement arrangement (HRA).
Because of this, these policies use lower premiums and out-of-pocket costs. PPO strategies offer more flexibility in choosing health service providers and services than HMO plans. But, they typically have greater premiums and deductibles, and need policyholders to submit their own claims for out-of-network care, which can be complicated and lengthy.
An HMO is a type of health insurance where a group of network medical professionals, hospitals, and other treatment providers contract with an insurance coverage supplier to offer insurance policy holders numerous covered services and products in exchange for a premium. Suppliers within the HMO network accept provide care to insurance policy holders at a decreased rate.
In 2023, 13% of employees in the U.S. with medical insurance coverage enrolled in an HMO plan1. Because these policies typically have lower premiums and out-of-pocket costs compared to other types of health insurance, they can appear like an appealing choice for those looking for coverage. The lower total costs come with specific restrictions.
Asset Strategies with Life Insurance
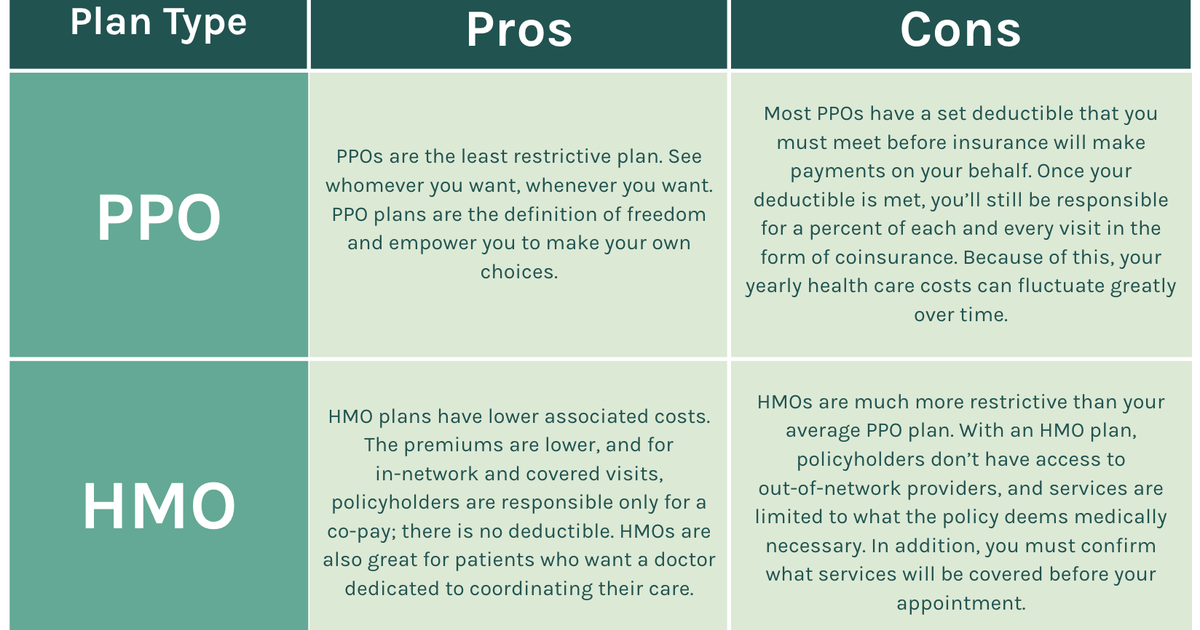
Their HMO likewise will not cover the costs of out-of-network care or treatment from a professional that took place without a PCP recommendation, except if an insurance policy holder requires emergency care. Before determining if an HMO matches you or your company, you must examine the benefits and drawbacks. HMO strategies usually have low premiums and copayments.
Insurance in Santa Ana CAYour strategy will likewise usually cover in-network expert care with only a little copay for services. When you enlist in an HMO plan, you have to pick a PCP who will be your primary point individual to connect to when you need care. In return, they coordinate your care, handle your general treatment, and make referrals for specialists.
Furthermore, your PCP functions as your medical advocate, and you might develop a strong bond with them, resulting in you receiving better and more constant care. While these benefits of HMO plans may appear enticing, there are prospective downsides that you should think about before registering. If you want your HMO to cover the cost of your care, you should get care from a specific network of suppliers in your area.
If you see a non-network service provider, you'll be responsible for your whole costs without the help of your insurance company. If you need to check out an expert for treatment, you need to ask your PCP for a referral for an in-network specialist in advance. If your PCP doesn't refer you, you need to pay the whole cost of the bill alone, which can be costly.
Your policy will lay out the situations that it considers an emergency. If your emergency doesn't fit the requirements in your strategy, you'll have to foot the bill by yourself. In 2023, the average yearly premium for a group HMO plan was $8,203 for self-only coverage and $23,758 for household coverage2.
Insurance in Santa Ana CAAnalyzing PPO Provider Flexibility versus Costs
For family coverage, companies contributed $16,600, and employees contributed $7,158. Like other kinds of health plans, HMO policies may have a yearly deductible. A deductible is the set amount of money a plan individual need to pay out-of-pocket before their insurance company begins to cover their medical care costs. In 2023, the typical deductible for an HMO strategy was $1,200.
KFF found that 33% of people registered in a self-only HMO don't have a deductible3. The 2023 out-of-pocket optimum for an Affordable Care Act (ACA) Market strategy was $9,100 for self-only coverage and $18,200 for household coverage4. In 2024, the optimum out-of-pocket limitation increased to $9,450 for individuals and $18,900 for households.
A PPO policy is a kind of health insurance in which an insurance coverage provider agreements with doctors, healthcare professionals, and medical centers to produce a list of "preferred" doctor for policyholders. When people with a PPO strategy get medical care from an in-network supplier, their health insurance company pays the provider at an agreed-upon lowered rate.
PPOs are the most typical strategy that companies use. In 2023, 47% of individuals with a group medical insurance strategy have a PPO2. These plans are popular because they don't need members to choose a PCP before enrolling and enable members to pick from a larger range of in-network companies than they can with an HMO plan.
PPO plans provide numerous benefits that make getting medical care a convenient and favorable experience. PPO plans have a large network of service providers providing the very same types of medical services with set comparable costs.

Latest Posts
Evaluating PPO vs HMO Medical Coverage

Essential Medicare Selection Advice in Next Year
Comparing PPO Vs HMO Medical Insurance for 2026