All Categories
Featured


Essential Medicare Selection Advice in Next Year
Table of Contents
An HMO Medicare Advantage plan provides a network (referred to as an "HMO network") of healthcare companies and medical facilities to its customers. It's required for a client to pick a primary care doctor to manage their healthcare and supply recommendations to any providers that are not in the plan's network, other than in the occasion of an emergency.
The ease of having a main care medical professional to coordinate and manage the care supplied. A client can just see providers within the plan's network unless they have a referral for an outside professional, or it's an emergency situation.
Nevertheless, unlike an HMO strategy, a PPO Medicare Advantage strategy enables more versatility when seeing out-of-network providers. It's not needed to have a referral to see an out-of-network expert although it may be more expensive and take additional time to get insurance protection since a patient must submit a claim for coverage each time they see an out-of-network provider.
The client has more versatility with which service providers they pick to see, whether they're within the strategy's network or out-of-network. Most times, there is no need for a referral if a patient cares to see an out-of-network specialist. Greater regular monthly premium. Probably, higher regular monthly premiums. The client is responsible for handling their healthcare rather of a primary care provider.
An EPO insurance coverage plan, or an 'Special Service provider Company' insurance coverage strategy, is frequently called a strategy that is "situated in between an HMO and PPO." This is because, like a PPO plan, an EPO does not need a patient to remain in-network for care meaning, no referrals or emergency situations are needed for seeing an out-of-network supplier.
Insurance in West Covina CAUnderstanding 2026 Medicare Enrollment Options for Seniors
This strategy is less commonly known, it frequently provides a much bigger network than an HMO.A POS insurance strategy, or a 'Point of Service' insurance coverage plan, is also understood to "blend elements of HMO and PPO plans." This is because, like an HMO strategy, a POS insurance strategy requires a client to have a medical care doctor that handles their health care and gives them referrals to out-of-network experts or suppliers.
The Medicaid program provides Americans with low to no expense health care to individuals/households that have actually limited income or specials needs. Alongside Medicaid is a program understood as CHIP or 'Children's Health Insurance Program,' which is a state moneyed program where patients pay low to no expense health care for kids and pregnant females who have limited income.
According to the internal revenue service, the deductible is at least $1,400 for an individual and $2,800 for a family. In order to combat the high deductible cost, it is suggested that a client contributes to an HSA/HRA or a 'Health Savings Account'/'Health Repayment Arrangement,' which employers frequently contribute to annually.
Another element to note about this strategy is that it secures the client from "devastating out-of-pocket expenses for covered services." What this suggests is that, once a client's "annual out-of-pocket expenses for covered services from in-network service providers, including deductibles, copayments, and coinsurance, reaches the established devastating limitation," the insurance provider will cover all expenses.
HMO and PPO strategies share particular features. There are some main differences between HMO and PPO strategies.
Evaluating PPO and HMO Insurance
HMOs will not cover care from an out-of-network supplier. HMOs normally have lower premiums and out-of-pocket expenses.
When it comes to health insurance, you have your choice of a number of strategy types. Differences between HMO (Health Maintenance Company) and PPO (Preferred Service provider Company) strategies include network size, capability to see professionals, costs, and out-of-network coverage.
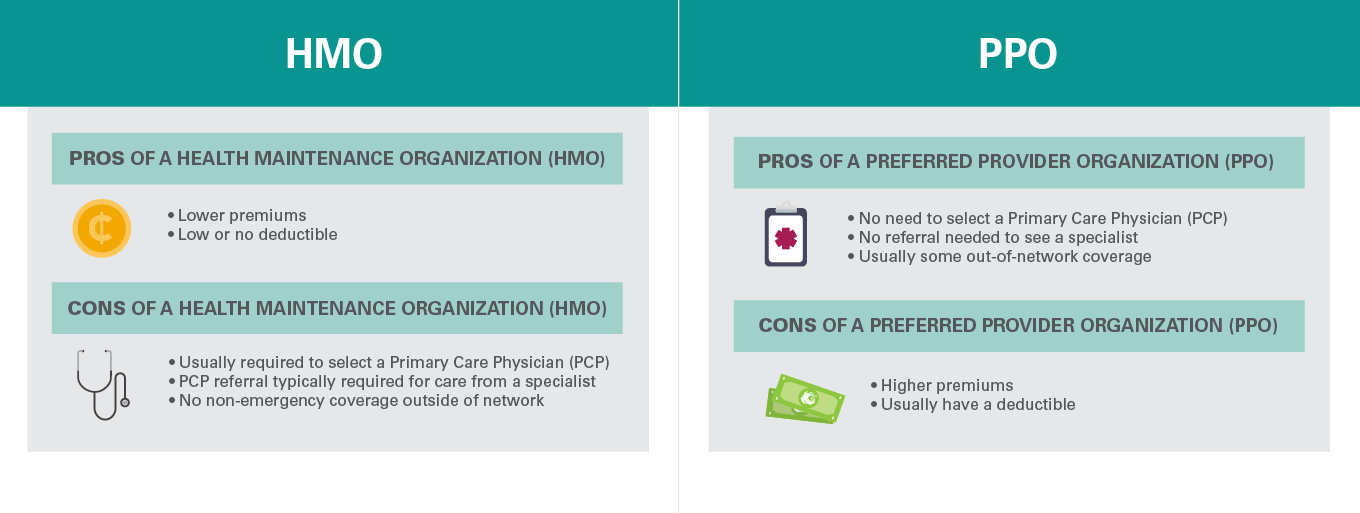
An HMO provides you access to specific medical professionals and healthcare facilities within its network. A network is comprised of suppliers that have consented to lower their rates for plan members and likewise meet quality standards. But unlike PPO strategies, care under an HMO strategy is covered just if you see a supplier within that HMO's network.

Latest Posts
Essential Medicare Selection Advice in Next Year
Comparing PPO Vs HMO Medical Insurance for 2026
Finding Cheap 2026 Health Insurance for Families